If You're an ARP Client, Your Lending Deserves the Same Attention as Your Insurance.
Access More Lenders. Get Better Advice. Pay Nothing Extra.
ARP helps you protect what you own. Wiser Home Loans helps you make sure the way you’ve borrowed to build it isn’t quietly working against you. Rob Wise is a mortgage broker and a property investor. He compares options across more than 70 lenders and structures loans with your long-term position in mind.
Rob Wise isn’t just a mortgage broker.
He’s a property investor with a $5M portfolio who became one.
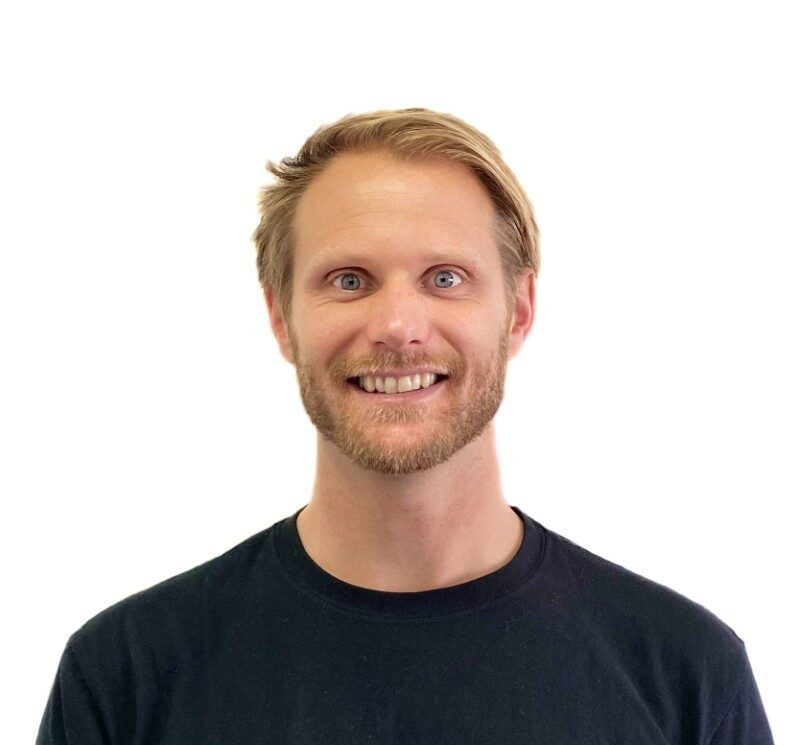
The Gold Coast mortgage broker with a $5 Million portfolio of his own.
Meet your broker, Rob Wise.
Rob spent over two decades working in civil engineering, town planning and property development before he created Wiser Home Loans. Along the way, he built a property portfolio of his own. From his first duplex to multiple properties worth over $5M today.
He’s accessed equity to fund new purchases. He’s refinanced when his structure stopped working. He’s bought within a trust and navigated what that means for lenders. He’s hit serviceability walls and found ways around them.
He didn’t learn any of this from a textbook. He learned it by doing it, and then by helping his clients do the same.
When Rob looks at your situation, he’s not just running numbers through a lender’s calculator. He’s thinking about what you’re trying to build, what could get in the way, and how to structure your lending so that today’s decision doesn’t limit tomorrow’s options.
“I started Wiser Home Loans because I wanted to give my clients the advice I wished I’d had when I was buying. Clear, honest, and genuinely focused on what’s right for the customer, not for the lender.” — Rob Wise
You protect your property with ARP. Is your lending just as well structured?
Most property owners review their insurance cover regularly. Their mortgage? Less often. Here's what can happen in the gap.
The loan you took out two or three years ago may no longer be the right fit.
Lending conditions change. Your financial position changes. The rate you were given as a new customer may look very different compared to what's available to a borrower in your position today. Most people don't find out until they ask, and most people never ask. If you haven't had your loan reviewed in the past two years, you don't know whether you're on competitive terms. That's a risk with a straightforward fix.
If your fixed rate is expiring in the next six months, the window to act is now.
When a fixed rate term ends, most lenders automatically roll borrowers onto their standard variable rate, which is frequently higher than rates available to new or switching customers. This is the single most predictable and avoidable cost in mortgage lending, but only if you plan for it before it happens, not after.
For investors: how your loans are structured today directly affects what you can borrow tomorrow.
Cross-collateralisation, interest-only periods running out without a plan, and loans held with lenders whose policies don't suit your growing portfolio. These are structural problems that build up quietly and become expensive to untangle. The earlier they're identified, the more options you have. Rob sees this regularly with investors who come to him having already bought two or three properties, and who have more capacity than they realise, or less flexibility than they thought.
If your property has grown in value, there may be equity you could use and don't know about.
As property values rise and loans are paid down, equity builds up. That equity can potentially be accessed for renovations, as a deposit for a next purchase, or for other purposes *subject to lender assessment and your overall borrowing position. Many property owners don't have a clear picture of what's actually available to them. A single conversation with Rob gives you that picture. *Equity access subject to lender assessment, property valuation and individual circumstances.
Comparing loans from a panel of leading lenders
Wiser Home Loans Pty Ltd · ABN 37 692 735 087 · Credit Representative 575264 authorised under Australian Credit Licence 389328
Whoever you are, wherever you’re at
We’ve got a path for you.
We regularly help borrowers in these four situations.
Buying your first home
You've never done this before. You're not sure how much you can borrow, what a good rate looks like, or how the process actually works. You just want someone to walk you through it clearly and make sure you don't make an expensive mistake. That's exactly what Rob does. He explains your options in plain English, helps you understand what different loan features mean in practice, and manages the whole application so you can focus on finding the right property.
Buying an investment property, first one or fifth
You want a broker who thinks like an investor, not just like a lender. Someone who understands that the structure of your loan today affects your ability to buy again in the future, and who will take that seriously when making recommendations. Rob is a property investor himself. He's grown his own portfolio to over $5M and navigated equity releases, refinances, trust structure purchases and tight serviceability challenges along the way. He brings that experience to your lending.
Refinancing, or wondering if you should
Maybe your fixed rate is about to expire. Maybe your life has changed since you took out your loan. Maybe you've just never reviewed it and you suspect you're paying more than you need to. Rob will review your current loan, compare it against what's available now, and tell you honestly whether switching is likely to benefit your situation, and if so, what's involved. If staying put makes more sense, he'll tell you that too. *Subject to individual circumstances and lender assessment.
Moving up, or converting your home into an investment
You've outgrown your current place, or you're thinking about keeping it as a rental when you move. Either way, your next move involves two properties, and getting the structure right matters a lot. Rob will map out your equity position, what you can borrow, and how to bridge from where you are to where you want to be, without overextending or painting yourself into a corner.
Whether you’re buying your first home, building an investment portfolio, or looking to refinance, Wiser Home Loans helps you find a loan that works for your life and your future.
How it works.
From first call to settlement.
Step 1 · The discovery call (30 minutes, no cost, no obligation)
Your job: tell Rob about your situation. Nothing to prepare, no documents needed. Tell Rob what you own, roughly what you owe, and what's on your mind, whether that's reviewing an existing loan, planning a next purchase, or just wanting a clearer picture of your position. He'll listen carefully and ask the right questions. By the end of the call: you'll know what your options look like, what (if anything) is worth addressing in your current lending, and what the next step is for your specific situation. Free. No obligation. You're not agreeing to anything by having the conversation.
Step 2 · If it makes sense to go further, Rob does the work
Your job: provide the documents Rob asks for. He'll tell you exactly what's needed. If your discovery call reveals something worth acting on (a review worth doing, a loan worth switching, a purchase worth planning), Rob runs a full assessment: your borrowing capacity, the right lender for your profile, the right structure for your situation. He'll present a written recommendation in plain English before anything is lodged. If the review shows your current position is already sound, Rob will tell you that and you're done, with the reassurance that you actually know where you stand. Most clients find the first call is useful regardless of outcome.
Step 3 and beyond · If you proceed, Rob manages the process
Once you're happy with the recommendation, Rob prepares and lodges your application. Complete, accurate and with the right supporting documents. He tracks progress with the lender, responds to their requests, liaises with your solicitor or conveyancer, and keeps you updated throughout. You won't be chasing anyone. Rob is your single point of contact from here to the day you settle. *Subject to lender assessment and individual circumstances.
Most clients receive their pre-approval within a few business days of submitting their application.
*Subject to lender criteria and individual circumstances.
Amazing service Rob and the team at Wiser Home Loans knows their stuff inside and out. The depth of knowledge he brings is impressive. lenders, products, your specific situation. Honest advice, no jargon, and he genuinely cares about getting the right outcome. Made the whole process easy. If you're on the Gold Coast and need a home loan, look no further. Highly recommend.
What working with Wiser Home Loans actually looks like.
Here’s what you get when you work with Rob. From first conversation to settlement.
A clear picture of what you can borrow, before you start looking.
In your first call, Rob will assess your income, expenses, existing debts and deposit position to give you a realistic borrowing capacity figure. Not a rough estimate from a calculator... an informed view based on how lenders will actually assess your application. This stops you wasting time looking at properties you can't finance.
A written loan recommendation explaining why Rob is suggesting it.
You'll receive a written proposal that compares your options and explains Rob's recommendation in plain English. The rate, the structure, the features that matter for your situation, and the trade-offs. You'll understand exactly what you're agreeing to and why.
A pre-approval you can actually rely on.
Rob prepares and lodges your application with the right supporting documents from the start, which reduces the chance of delays, conditions or surprises further down the track. A well-prepared application is more likely to reach formal approval smoothly. *Subject to lender assessment and individual circumstances.
Someone managing the process so you don't have to.
Once your application is lodged, Rob tracks it with the lender, responds to their queries, coordinates with your conveyancer or solicitor, and keeps you updated at every step. You won't be chasing anyone. You won't be left wondering what's happening. You'll have one person who has it all in hand.
For investors: a loan structured with your next purchase in mind.
Rob is a property investor himself. He doesn't just process your current loan — he thinks about how the structure of today's lending affects your ability to borrow again in the future. He'll help you understand how different structures may affect your borrowing capacity, cash flow and long-term options. This is lending guidance, not investment advice — but it's the kind of thinking most brokers don't bring to the table. Disclaimer: general lending guidance only, not financial or investment advice.
Questions we get asked a lot.
I'm not sure if I'm ready to apply for a loan. Is it too early to call?
It’s almost never too early. A lot of the value Rob provides happens before you’re ready to apply, helping you understand your position, what you’d need to do to strengthen your application, and what timeline makes sense. If you’re thinking about buying in the next 6–12 months, talking to Rob now gives you a head start.
How long does the process take?
It varies depending on your situation, the lender, and how quickly documents can be gathered. Once your application is submitted, most lenders take anywhere from a few business days to a couple of weeks to reach formal approval. We’ll keep you informed at every step and work hard to keep things moving. *Subject to lender processing times and individual circumstances.
Can you help if I'm self-employed or have complex income?
Yes. We regularly work with clients who are self-employed, have irregular income, or receive rental income from investment properties. Different lenders assess income differently. Part of our job is finding the lender whose criteria aligns with your situation. *Subject to lender criteria and individual assessment.
Do you work with property investors on the Gold Coast?
Yes. Wiser Home Loans specialises in helping Gold Coast investors structure their lending for long-term borrowing capacity, equity use and portfolio growth. Rob, our senior broker, is a property investor himself with a 5-property portfolio.
What’s the best loan structure for an investment property?
The best structure depends on your borrowing capacity, income, existing loans and long-term plans. We help investors choose structures that protect flexibility and future servicing without giving financial advice.
How do I use equity from my current home to buy an investment property?
We can assess your property’s usable equity and help structure your investment loan without cross-collateralising your properties. This keeps your lending cleaner and more flexible for the future.
Can you help me buy multiple investment properties over time?
We design lending strategies that show how today’s loan choices may affect your borrowing power for future purchases. This is lending guidance, not investment advice.
Can you help with refinancing investment loans?
Absolutely. We review your current rates, structure, and lending position to see if refinancing can improve your cash flow or borrowing power.
Have a different question? Get in touch.
The four situations where a call with Rob is worth 30 minutes of your time.
Here's why getting lending advice early tends to matter more than people expect:
"I have investment properties and I'm not sure my loans are structured the right way."
Rob will map your full lending position: what properties you hold, how they're financed, your loan-to-value ratios, whether your structures are supporting or limiting your next move. If something needs attention, he'll tell you clearly and explain why. If everything looks sound, he'll tell you that too. As a property investor himself with a $5M+ portfolio, Rob understands what you're building, not just the paperwork behind it. *Lending guidance only, not financial or investment advice.
"I've had my home loan for a few years and I've never really looked at whether it's still competitive."
Rob will review your current loan (rate, structure, features), and compare it honestly against what's available to a borrower in your position today. He'll factor in the costs of switching (discharge fees, any break costs) and give you a clear picture of whether staying put or switching makes more financial sense for your situation. If the numbers don't support switching, he'll say so. Rate comparisons based on market at time of assessment. *Subject to individual circumstances.
"I'm thinking about buying another property and I want to understand what I can actually borrow."
Rob will assess your borrowing capacity properly, not with a calculator, but based on how lenders will actually assess your income, expenses, existing debt and deposit position. He'll identify the lenders most likely to suit your profile, flag any structural issues with your existing loans to address first, and tell you what realistic timeline and price range to plan around. The earlier you have this conversation, the more time you have to position yourself before you need to act.
"My fixed rate is coming up for renewal and I want to know what my options are."
Rob will get your current loan details, work out what you'd revert to if you did nothing, compare that against what's currently available, and give you a clear recommendation, along with the actual costs of switching so you can make an informed decision. The window to act before a fixed rate expiry is typically three to six months before the end date. If that's where you are, this is the right moment to call. Subject to lender assessment and individual circumstances. Variable rates subject to change. The earlier you have this conversation, the more time you have to position yourself before you need to act.
Ready to take the next step?
Book a free 30-minute call with Rob. Tell him about your situation. He'll give you an honest picture of what you can borrow, what your options look like, and whether now is the right time to move, or what you'd need to do to get there.